Entrepreneurship: Turning Ideas into Opportunities

Entrepreneurship is one of the most powerful drivers of economic growth, innovation, employment, and social development. It is the process of identifying opportunities, organizing resources, taking calculated risks, and creating value through a new business, product, service, or social initiative. An entrepreneur is not simply a person who starts a company; an entrepreneur is someone who recognizes a problem or unmet need and develops a practical solution that can create economic or social value.

For owners preparing for a future transaction, Fractional CFO services can also help strengthen financial reporting, forecasting, cash-flow planning, and performance analysis, giving management a clearer picture of the company’s financial position well before a potential sale.

In today’s rapidly changing world, entrepreneurship has become increasingly important. Technology, globalization, digital platforms, changing consumer behavior, and new business models have opened opportunities for individuals to start enterprises with relatively limited resources. From small local businesses and technology startups to social enterprises and creative ventures, entrepreneurship can take many forms.

The Meaning of Entrepreneurship

Entrepreneurship begins with an idea, but a successful enterprise requires much more than an idea. Entrepreneurs must understand the market, identify potential customers, estimate costs, develop products or services, arrange finance, build teams, promote their businesses, and continuously respond to competition and changing market conditions.

Entrepreneurs usually operate in situations where the future is uncertain. They may not know whether customers will accept their product, whether competitors will enter the market, or whether their financial resources will be sufficient. Therefore, entrepreneurship requires careful planning as well as the willingness to take calculated risks.

Successful entrepreneurs do not necessarily avoid risk. Instead, they try to understand, manage, and reduce risk through research, experimentation, financial planning, and continuous learning.

Importance of Entrepreneurship

Entrepreneurship contributes significantly to economic development because new enterprises generate employment and create new sources of income. Small and medium-sized businesses, in particular, provide large numbers of jobs across manufacturing, services, retail, agriculture, construction, technology, tourism, and other sectors.

Entrepreneurship also encourages innovation. Entrepreneurs frequently introduce new products, services, technologies, production methods, and business models. For example, digital payment systems, online education platforms, food delivery services, renewable-energy solutions, and e-commerce businesses have emerged partly because entrepreneurs identified changing needs and developed new ways of meeting them.

Another important contribution of entrepreneurship is competition. New businesses challenge existing firms, encouraging companies to improve quality, reduce costs, adopt technology, and offer better services to customers.

Entrepreneurship can also contribute to regional development. Enterprises established in smaller towns and rural areas can generate local employment, support local supply chains, and reduce excessive dependence on major metropolitan areas.

Characteristics of Successful Entrepreneurs

Successful entrepreneurship is often associated with a combination of personal qualities, managerial skills, and practical experience.

One important characteristic is vision. Entrepreneurs must be able to recognize opportunities that may not be immediately obvious to others. They should understand how customer needs, technology, society, and markets may change over time.

Another important quality is creativity. Entrepreneurship often involves finding new solutions to existing problems. Creativity may appear in product design, marketing, service delivery, pricing, distribution, or the use of technology.

Entrepreneurs also need resilience. Business activities rarely develop exactly according to plan. Entrepreneurs may experience financial difficulties, unsuccessful products, customer complaints, competition, or unexpected market changes. The ability to learn from setbacks and continue improving is therefore essential.

Communication and leadership are equally important. Entrepreneurs frequently need to communicate with employees, customers, investors, suppliers, government agencies, and business partners. Strong communication helps them explain their vision, negotiate agreements, attract customers, and build effective teams.

Financial literacy is another critical skill. Entrepreneurs should understand basic concepts such as revenue, expenditure, profit, cash flow, investment, working capital, pricing, and break-even analysis. A business may have a good product and still fail if its finances are poorly managed.

From an Idea to a Business

The entrepreneurial journey usually begins with identifying a problem or opportunity. Instead of asking, “What business should I start?” aspiring entrepreneurs can ask, “What problem can I solve?”

After identifying an opportunity, the entrepreneur should conduct market research. This involves understanding potential customers, competitors, pricing, demand, and market trends.

The next stage is developing a business model. Entrepreneurs need to determine what they will offer, who their customers will be, how the product or service will be delivered, and how the business will earn revenue.

Before investing heavily, entrepreneurs can test their idea on a small scale. A prototype, pilot project, sample service, or minimum viable product can help determine whether customers are genuinely interested.

Customer feedback is extremely valuable at this stage. It allows entrepreneurs to improve their products before making larger investments.

Role of Technology in Entrepreneurship

Technology has dramatically changed entrepreneurship. A business can now communicate with customers, receive payments, advertise products, manage accounts, collaborate with teams, and sell internationally using digital platforms.

Social media has made marketing more accessible to small businesses. Entrepreneurs can use digital platforms to demonstrate products, communicate directly with customers, build communities, and develop brands.

Artificial intelligence, cloud computing, data analytics, automation, and digital payment systems are also creating new entrepreneurial opportunities. Businesses can use these technologies to improve productivity, understand customer preferences, and reduce operating costs.

However, technology should be viewed as a tool rather than a substitute for a good business idea. Successful businesses still require customer understanding, quality, reliability, trust, and effective management.

Entrepreneurship and Innovation

Innovation is closely connected with entrepreneurship. Innovation does not always mean inventing a completely new technology. It can also involve improving an existing product, developing a better service, introducing a new delivery system, or making an existing solution more affordable.

A local entrepreneur, for example, may create an innovative agricultural supply chain that connects farmers directly with consumers. Another entrepreneur may develop an online platform to provide affordable professional training. Both examples demonstrate innovation even if the underlying technologies already exist.

The most successful innovations usually provide meaningful value to users.

Challenges Faced by Entrepreneurs

Entrepreneurship can be rewarding, but it also involves significant challenges. Access to finance is one of the most common difficulties, particularly for first-time entrepreneurs. Banks and investors may hesitate to support businesses without an established financial history.

Finding skilled employees, attracting customers, managing cash flow, complying with regulations, and dealing with competition can also be difficult.

Entrepreneurs must therefore develop networks and seek support from mentors, incubators, industry associations, universities, government programs, and experienced professionals.

Another challenge is maintaining balance between growth and sustainability. Rapid expansion without adequate systems, financing, or management can create serious problems. Sustainable growth is generally more valuable than expansion that cannot be supported financially or operationally.

Social Entrepreneurship

Entrepreneurship is not limited to profit-making businesses. Social entrepreneurship focuses on solving social or environmental problems through innovative and financially sustainable approaches.

Social entrepreneurs may work in education, healthcare, sanitation, renewable energy, waste management, affordable housing, rural development, or skill development. Their goal is often to combine financial sustainability with measurable social impact.

This approach demonstrates that entrepreneurship can contribute not only to economic development but also to improving quality of life.

The Future of Entrepreneurship

The future of entrepreneurship is closely connected with digital transformation, sustainability, artificial intelligence, clean technologies, healthcare innovation, education technology, financial technology, smart cities, and the circular economy.

Consumers are becoming increasingly aware of environmental and social issues. As a result, businesses that provide environmentally responsible products, efficient resource use, ethical practices, and transparent operations may find growing opportunities.

Young entrepreneurs will also have increasing access to online learning, global markets, digital tools, crowdfunding platforms, and professional networks. These resources can reduce some traditional barriers to starting a business.

Conclusion

Entrepreneurship is ultimately about creating value by transforming ideas into practical solutions. It requires creativity, planning, courage, discipline, adaptability, and continuous learning. Entrepreneurs identify opportunities where others may see problems and attempt to create solutions that benefit customers, communities, and economies.

Not every entrepreneurial idea becomes successful, and failure is an inherent possibility in business. However, the entrepreneurial process itself encourages experimentation, innovation, problem-solving, and learning.

For students, professionals, researchers, and aspiring business owners, developing an entrepreneurial mindset can be valuable even without immediately starting a company. Learning to identify opportunities, evaluate risks, communicate ideas, manage resources, and solve problems can contribute to success across many professions.

Entrepreneurship therefore represents much more than business ownership. It is a mindset focused on opportunity, innovation, value creation, and positive change. In an increasingly dynamic and competitive world, entrepreneurs will continue to play a major role in shaping industries, creating employment, introducing new technologies, and developing solutions for the challenges of the future.

Daily writing prompt
How do you make time for self-care?

How AI Is Reshaping Commercial Real Estate Investment Analysis and Deal Evaluation

Commercial real estate has long been one of the most data-intensive industries in the world, yet for decades it relied on manual spreadsheets, fragmented databases, and the subjective judgment of individual analysts. That era is ending. Artificial intelligence is now penetrating every layer of the CRE investment lifecycle — from initial deal screening to long-term asset management — and the firms that adapt earliest are gaining a measurable competitive edge. Understanding how this transformation is unfolding, and which tools are driving it, is essential for any investor, broker, or asset manager operating in today’s market.

The Data Problem That Has Always Plagued CRE

Unlike equities or fixed income, commercial real estate lacks a centralized exchange. Pricing is opaque, transaction data is often delayed or incomplete, and comparable analysis requires significant manual effort. A single underwriting package for a mid-market office or industrial asset can involve dozens of variables — rent rolls, lease abstracts, operating expense histories, market vacancy trends, cap rate benchmarks, and debt service assumptions — all of which must be synthesized quickly if a deal is to be evaluated competitively.

This fragmentation has historically created two problems. First, smaller investment shops without large analyst teams are structurally disadvantaged against institutional players who can throw more human capital at due diligence. Second, even well-resourced firms are vulnerable to errors and blind spots when analysts are overwhelmed by deal volume. AI addresses both problems simultaneously by automating data aggregation, standardizing financial modeling inputs, and surfacing risk signals that human reviewers might miss under time pressure.

Underwriting at Machine Speed

One of the most immediate applications of AI in commercial real estate is accelerating the underwriting process. Traditional underwriting timelines — often measured in days or weeks — are being compressed to hours. Machine learning models trained on historical transaction data can generate preliminary valuations, stress-test rent assumptions against market scenarios, and flag properties where the seller’s pro forma appears optimistic relative to actual submarket performance.

This speed advantage is not merely operational. In competitive deal environments, the ability to deliver a credible, data-backed offer faster than a rival bidder can be the difference between closing and losing a transaction. AI-powered underwriting tools also reduce the cognitive load on senior analysts, allowing them to focus on qualitative judgment — tenant credit quality, local market relationships, repositioning potential — rather than spending hours building and checking financial models from scratch.

Scenario Modeling and Sensitivity Analysis

Beyond base-case underwriting, AI enables more sophisticated scenario modeling than most teams could realistically produce manually. Dynamic sensitivity analyses — showing how IRR and equity multiple shift across dozens of combinations of rent growth, exit cap rate, and financing assumptions — can be generated instantly and updated in real time as market conditions change. This gives investment committees a far richer picture of downside risk and return distribution than a single-point estimate ever could.

AI-Driven Demand Signals in Commercial Real Estate

The influence of AI extends beyond internal investment processes. It is also reshaping the physical demand landscape for commercial real estate itself. Data centers, AI research campuses, and advanced manufacturing facilities are among the fastest-growing property types in the current cycle, driven directly by the infrastructure requirements of the AI industry. According to JLL’s analysis of how AI is creating new demand in commercial real estate, the buildout of AI infrastructure is generating significant absorption across industrial, data center, and specialized office segments — a trend that sophisticated investors are actively positioning around.

Understanding these demand signals requires exactly the kind of real-time data synthesis that AI platforms are designed to provide. Investors who can identify emerging AI-driven demand corridors before they become consensus trades will capture the most attractive entry points.

Asset Management and Portfolio Optimization

The value of AI in commercial real estate does not end at acquisition. Post-close asset management is equally transformed. AI systems can monitor lease expirations, track tenant financial health, benchmark operating expenses against peer properties, and generate hold-versus-sell analyses on a continuous basis rather than as a periodic exercise. This shifts asset management from a reactive discipline — responding to problems as they emerge — to a proactive one, where risks are identified and addressed before they affect returns.

Natural Language Processing in Lease Abstraction

One particularly impactful application is natural language processing applied to lease abstraction. Extracting critical economic and legal terms from complex commercial leases has traditionally required hours of attorney or paralegal time per document. NLP models can now perform this task in minutes with high accuracy, dramatically reducing due diligence costs and enabling investors to analyze larger deal volumes without proportional increases in overhead.

Interestingly, the same advances in real-time language processing that are enabling faster lease abstraction and document analysis in CRE are also powering broader AI applications. Researchers exploring fast-response text-to-speech engines for real-time AI companions are developing the underlying language model infrastructure that increasingly informs how AI platforms process and communicate complex information — a convergence that will continue to benefit enterprise AI tools across industries, including real estate.

NOAL: Bringing Institutional-Grade AI to CRE Professionals

Among the platforms emerging to meet this moment, NOAL stands out for its focused approach to the commercial real estate investment workflow. Noal is an AI-powered commercial real estate platform built specifically around the disciplines that matter most to CRE professionals: underwriting, investment analysis, deal evaluation, financial modeling, and asset management. Rather than offering a generic AI assistant layered on top of existing tools, NOAL is purpose-built for the specific analytical demands of the CRE industry, integrating the data inputs and output formats that investment teams actually use.

This specialization matters. Generic AI tools require significant customization and prompt engineering to produce outputs that meet the standards of institutional real estate analysis. A platform designed from the ground up for CRE workflows can deliver accurate, actionable results with far less friction, allowing teams to move faster without sacrificing analytical rigor.

The Competitive Imperative

The adoption curve for AI in commercial real estate is steepening. Early adopters are already reporting meaningful improvements in deal throughput, underwriting accuracy, and portfolio performance monitoring. As these advantages compound over time — better deals sourced, fewer errors in underwriting, more proactive asset management — the gap between AI-enabled firms and those still relying on legacy processes will widen.

For investment managers, developers, and brokers, the question is no longer whether AI will transform commercial real estate. It already is. The question is whether your organization will be positioned to capture the benefits of that transformation or find itself competing at a structural disadvantage against peers who moved earlier.

Conclusion

Artificial intelligence is not a distant future for commercial real estate — it is the present competitive landscape. From accelerating underwriting timelines and enabling richer scenario analysis to identifying AI-driven demand trends and optimizing portfolio performance, the applications are concrete, measurable, and growing. Platforms purpose-built for the CRE investment workflow are making institutional-grade analytical capabilities accessible to a broader range of market participants, leveling a playing field that has historically favored the largest and most resource-rich firms. For professionals serious about staying ahead in this environment, understanding and adopting the right AI tools is no longer optional — it is a strategic necessity.

Daily writing prompt
What’s a place you visited that felt like home?

Roosh Ventures, Sergey Tokarev’s Venture Fund, Entered the Prestigious Sifted Ranking

Sergey Tokarev’s Ukrainian investment fund Roosh Ventures entered the top 50 investors in France and the Benelux

Investment fund Roosh Ventures, which invests in technology startups in different regions of the world, became the first and only Ukrainian representative in the Sifted ranking. It took 43rd place in the top 50 lenders and investors in France, Belgium, the Netherlands and Luxembourg. In addition, three portfolio companies — Folk, Alma and Gladia — entered the list of the region’s fastest-growing startups. This was announced by Sergey Tokarev, a co-founder of Roosh Ventures, investor and technology entrepreneur.

Sifted Ranking: How the Ukrainian Venture Fund Achieved This

Leading European media outlet Sifted specialises in startups and technology businesses, analyses the venture capital market, compiles authoritative rankings and covers news. When evaluating companies, it considers a set of criteria, including the quality of the formed portfolio, the player’s impact on the development of the local ecosystem and the intensity of completed deals.

Three Roosh Ventures portfolio companies were recognised by Sifted:

  • Folk creates a CRM platform that gives people, rather than algorithms, control over business relationships.
  • Alma is scaling a powerful payment system with a focus on the model of responsible consumption.
  • Gladia develops infrastructure based on artificial intelligence for speech analysis and transcription.

This selection, which brings together innovations from different sectors, demonstrates the fund’s overall investment priorities.

“The appearance of a venture fund from Ukraine among the best demonstrates that the place of registration is no longer a determining factor for the scaling and competitiveness of venture capital. Previously, most positions were allocated to local European funds, so the presence of a Ukrainian player on this list makes it stand out against the general background,” says Sergey Tokarev.

The entrepreneur is confident that this result became possible precisely because of Roosh Ventures’ approach to selecting projects.

“What happened is not a coincidence. It cannot be called an ordinary line in a ranking. By entering the top 50 investors in France and the Benelux, we proved that Ukrainian venture funds are already playing in the top league among European countries,” says co-founder of Roosh Ventures.

The result of the Sifted ranking, which included Roosh Ventures and three of its portfolio companies, is becoming part of a broader trend in which Ukrainian investment and technology teams are increasingly becoming competitors to Western players. For an investor who operates at the intersection of business, technology and social impact, the presence of the venture fund in a European ranking is proof of the right strategy, not an end in itself.

Daily writing prompt
If you had to switch lives with a fictional character for a week, who would you choose?

Touchstone Digital Solutions Unveils Digital Donor Wall Platform, Redefining Philanthropic Recognition for Universities, Schools and Nonprofits

New interactive, cloud-based donor recognition systems replace static engraved plaques with dynamic storytelling, real-time updates and measurable fundraising impact

BEDFORD, NH – August, 2026 — Touchstone Digital Solutions, a provider of digital donor recognition technology, today announced the expansion of its Digital Donor Walls platform, a cloud based system designed to help universities, schools and nonprofit organizations modernize the way they honor their most generous supporters.

For decades, institutions have relied on physical, engraved donor walls to acknowledge contributions. According to the company, these static displays are increasingly unable to capture the scale of modern giving campaigns or convey the ongoing impact of donor generosity . Touchstone’s Digital Donor Wall addresses this gap by combining high resolution visuals, animation and storytelling elements with a secure, easy to manage software backend.

A Shift From Static Plaques to Dynamic Storytelling

The Digital Donor Wall system allows organizations to move beyond simple name listings. Institutions can showcase donor names, giving levels and personalized messages in animated layouts, while integrating video, photo galleries and infographics that demonstrate the tangible outcomes of contributions . Visitors are able to interact with the displays, filtering by campaign or giving to society and exploring individual donor stories, creating a more immersive recognition experience than traditional signage allows.

A key feature of the platform is real-time content management. Donor services teams can add new names, launch new campaigns or update information instantly through a secure online dashboard, without requiring technical expertise. Touchstone positions this as a direct alternative to the recurring costs associated with physical re-engraving, which the company notes can exceed 1,500 US dollars each time a donor list requires updating or an additional panel is needed.

“We view donor recognition not as a static transaction but as an ongoing relationship,” said a Touchstone Digital Solutions spokesperson. “Our platform gives institutions the ability to keep that relationship alive visually, updating instantly as their community and their campaigns grow, rather than freezing recognition in wood or bronze the moment it is installed” .

Scalable Across Sectors

The company said the platform has been built to scale from small installations of roughly 100 donors to large, multi-screen deployments recognizing more than 100,000 supporters, making it applicable across a wide range of institutional sizes and missions.

In higher education, the system is designed to recognize alumni, faculty and benefactors, celebrate scholarship recipients, mark facility dedications and present historical timelines of institutional giving, typically installed in student unions, alumni centers or library entrances. Hospitals and health organizations can use the walls to highlight patient success stories, showcase donor-funded medical technology and recognize foundation leadership societies, often in main lobbies or waiting areas. Schools can apply the technology to recognize PTA members, capital campaign donors and local business partners during events such as parent-teacher nights and open houses .

A third party industry observer said the shift reflects a broader trend in institutional communications. “Donor recognition has traditionally been treated as a fixed cost buried in a capital project budget,” the spokesperson said. “What we’re seeing now is organizations treating digital recognition wall displays as active engagement tools that can be measured, updated and tied directly to future fundraising performance, rather than a one time installation that becomes outdated within a few years”.

Positioned as a Long term Investment

Touchstone frames the Digital Donor Wall as a long-term financial and stewardship asset rather than a one-time capital expense. The company’s investment materials cite comparative cost scenarios in which digital solutions offer meaningful long term savings relative to traditional engraving once repeated updates, additions and panel expansions are factored in over time. Beyond cost, the company argues that visible, dynamic displays of community impact serve as a persuasive tool for prospective donors evaluating whether to contribute to an organization.

The company’s implementation process follows five stages: discovery and strategy sessions to understand an organization’s goals and brand; custom interface design; development and integration with existing donor databases; hardware deployment including large format screens and touchscreen kiosks with staff training; and ongoing support to keep content current. Touchstone said its US-based support team remains engaged with client organizations after launch to ensure displays continue to perform and evolve alongside institutional needs.

The Digital Donor Wall platform is available now to universities, colleges, K-12 schools and mission driven nonprofit organizations across the United States seeking to modernize donor stewardship and strengthen long-term fundraising relationships.

About Touchstone Digital Solutions

Touchstone Digital Solutions designs and deploys custom digital donor recognition systems for universities, schools and nonprofit organizations across the United States. The company combines interactive display technology, cloud based content management software and dedicated US based support to help mission driven institutions transform static donor recognition into dynamic, ongoing storytelling that strengthens community engagement and supports long-term fundraising success.

Media Contact

Touchstone Digital Solutions

8 Powder Hill Road, Bedford, NH 03110

Phone: (603) 361-7541

Email: info@touchstone-ds.com
Website: https://touchstone-ds.com/

Daily writing prompt
What’s the best thing you’ve ever found randomly on the street?

An Overview of Consumer Protection Law in the UK

Consumer protection in the UK is often discussed transaction by transaction – a specific refund dispute, a specific faulty product – but it is worth stepping back occasionally to see the structure behind those individual rules. Understanding who actually enforces consumer law, and under which legislation, changes how a dispute is approached from the very first message to a seller.

Two Statutes at the Core of the System

The current enforcement framework rests primarily on two pieces of legislation: the Consumer Rights Act 2015 and the more recent Digital Markets, Competition and Consumers Act 2024. Between them, these two statutes cover contract quality, unfair trading practices, and the regulatory powers used to act against non-compliant businesses.

Who Actually Enforces These Rules

The Competition and Markets Authority is the principal national authority responsible for both competition and consumer protection in the UK, with a remit spanning competition law, consumer rights, the UK internal market, and subsidy control. It investigates cases, issues rulings, and can impose penalties directly, rather than simply advising on disputes from the sidelines.

The Role of Local Trading Standards

Alongside the CMA, Trading Standards services operate at a local level and remain the more accessible route for an individual consumer with a specific complaint. National Trading Standards coordinates cross-boundary, intelligence-led enforcement projects across England and Wales, bringing local representatives together to prioritise and fund cases that a single local authority could not realistically pursue alone. This two-tier structure – national authority plus local enforcement – is what allows both large-scale unfair trading investigations and individual local disputes to be addressed within the same overall system.

For an individual consumer or a small business trying to work out which rules actually apply to a specific dispute, this layered structure can be genuinely confusing. Rather than guessing which statute or regulator is relevant, a short session with Consultant platform usually clarifies the right starting point faster than searching through primary legislation directly.

Why the Structure Matters for Ordinary Disputes

Knowing that Trading Standards, not the CMA, is typically the first point of contact for an individual consumer complaint saves time that would otherwise be spent contacting the wrong body entirely. Conversely, patterns affecting many consumers – misleading pricing across an entire sector, for example – are more likely to fall within the CMA’s own investigative remit rather than a single local Trading Standards office.

A System Still in Motion

The 2024 Act significantly expanded the CMA’s direct enforcement powers, moving away from a system that relied heavily on court action for many cases. This shift is still being absorbed by businesses and consumers alike, which means guidance that was accurate under the older enforcement model may no longer reflect how a dispute is actually handled today.

Sector Regulators Add Another Layer

Certain industries – financial services, telecoms, energy – have their own dedicated regulators operating alongside the CMA and Trading Standards, each with concurrent powers to enforce consumer protection law within their specific sector. A dispute involving a broadband contract, for instance, may ultimately involve Ofcom’s framework rather than a general consumer protection route, even though the underlying legal principles overlap significantly with the Consumer Rights Act.

What This Means for Businesses Operating Across Sectors

A business that sells both general consumer goods and a regulated service, such as a retailer offering financing options alongside physical products, can find itself answerable to more than one regulatory body at once. Understanding which authority actually has jurisdiction over a specific complaint, before responding to it, avoids wasted effort addressing the wrong regulatory framework entirely.

Daily writing prompt
If you could go back and witness any historical event, which one would you pick?

Why Modern Enterprises Are Prioritizing Premium Accommodations for Executive Travel

Corporate travel is undergoing a significant transformation. For decades, enterprise travel policies were strictly driven by budget constraints, often prioritizing the lowest possible upfront costs over the actual experience of the employee. Today, forward-thinking organizations are rethinking this approach entirely. They are discovering that cutting corners on executive travel can inadvertently lead to exhausted leaders, reduced productivity, and ultimately, a much lower return on investment.

Instead of viewing corporate trips merely as a financial expense, modern enterprises are beginning to measure the return on time and return on experience to gauge how well a trip supports employee collaboration. According to recent industry reports, corporate investments in premium travel can deliver an impressive return on investment by recovering executive time value and avoiding logistical disruptions. Furthermore, employees themselves are demanding better conditions. Studies reveal that a vast majority of business travelers are willing to spend their own money to secure perks that reduce travel fatigue, highlighting a clear gap between standard corporate policies and actual traveler needs.

Strategizing Location and Transit Efficiency

One of the most effective ways to reduce travel fatigue is to minimize the time spent in transit between the airport, the hotel, and the boardroom. Modern executives simply do not have the time or the patience to navigate complex inner-city transfers after a long, exhausting flight. Strategic location planning has therefore become a critical factor in corporate travel management, keeping executives closer to major transit hubs and essential business districts.

Take Osaka as a prime example of a rapidly expanding international business epicenter. The city is a major hub for global commerce, bolstered by direct connectivity to dozens of global cities. However, navigating its vast urban sprawl can be daunting for international visitors. Smart corporate travel managers know that placing executives at a 5 star hotel in Namba provides immediate access to the primary southern commercial gateway of the city. Because the Namba district directly connects to the international airport via express trains in just over half an hour, business leaders can bypass local traffic entirely. This strategic placement allows them to check in quickly, refresh, and get straight to work without unnecessary delays.

The Hidden Costs of Travel Fatigue

The reality of frequent business trips is often far less glamorous than it appears from the outside. Navigating crowded airports, adapting to new time zones, and managing a full schedule of meetings can quickly deplete an executive’s energy. This constant movement takes a very real toll on physical and mental health. According to a recent survey by World Travel Protection, 46% of business travelers report increased stress and burnout from frequent work trips, a figure that rises considerably for those who travel every two months.

To mitigate these alarming statistics, companies are recognizing that rest and recovery are non-negotiable components of a successful business trip. When leaders are well-rested, they are sharper, more focused, and better equipped to handle high-stakes negotiations. Corporate planners are actively seeking out accommodations that offer more than just a place to sleep. They are looking for environments designed to reduce friction, provide exceptional comfort, and actively counteract the mental toll of life on the road.

Essential Amenities for High-Performing Teams

Premium accommodations are no longer defined solely by luxurious decor or high thread counts. For the modern business traveler, luxury is synonymous with efficiency, connectivity, and wellness. Enterprises are now specifically filtering their accommodation choices based on specialized amenities that support a demanding work schedule. When reviewing corporate travel strategies published by the International Journal of Research, it becomes clear that premium travel services play a vital role in streamlining daily logistics. By offloading tasks to dedicated hotel concierges or utilizing well-equipped business centers, travelers can maintain their focus on their core business objectives rather than basic administrative tasks.

To ensure their teams perform at their highest capacity, companies look for the following essential amenities when booking premium accommodations:

  • Robust Digital Infrastructure: A reliable internet connection is no longer optional. Industry data shows that corporate travelers consider high-speed wireless internet their top required amenity, with nearly half indicating they would cancel a booking without it.
  • Wellness and Fitness Facilities: Modern corporate travelers strongly prioritize their physical well-being. A significant portion of business travelers actively seek out on-site fitness centers, spas, and relaxation facilities to decompress after a long day of meetings.
  • Ergonomic Workspaces: The physical strain of working from a poorly designed hotel desk can lead to serious discomfort. Providing ergonomic workspaces for remote and traveling employees is highly effective, as companies offering these setups see a notable reduction in reported work-related musculoskeletal complaints.
  • Healthy Dining Options: Access to nutritious food at all hours is crucial for maintaining energy levels and focus, especially when dealing with jet lag or irregular meeting schedules. C-suite travelers actively choose accommodations focused on strict time boundaries and healthy dining to combat the physical toll of travel.

A Calculated Investment in Enterprise Success

The evolution of corporate travel policies reflects a broader understanding of how employee well-being directly impacts overall enterprise success. By moving away from restrictive budgets and embracing the strategic advantages of premium accommodations, companies are protecting their most valuable assets.

Investing in high-quality travel experiences, strategic locations, and essential wellness amenities is no longer viewed as an unnecessary luxury. Instead, it is a calculated business decision that yields a substantial return on investment through sustained productivity, reduced burnout, and sharper decision-making. As global business travel continues to evolve, the organizations that prioritize executive comfort will undoubtedly maintain a competitive edge in the marketplace.

Daily writing prompt
Share a photo of your pet and tell us one thing that makes them uniquely them.

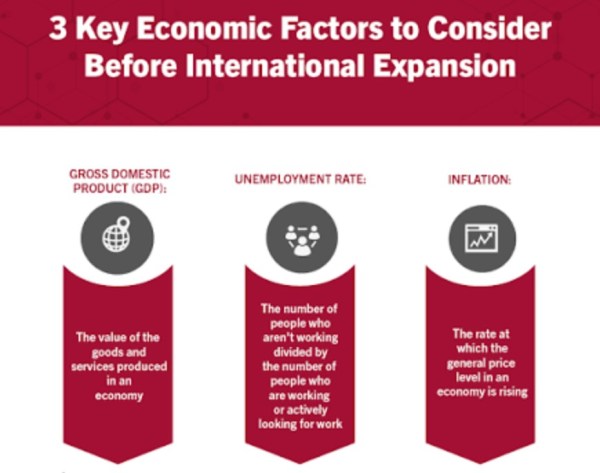
Essential Strategies for Expanding a Service-Based Business into International Markets

The global economy is undergoing a massive structural shift. For decades, international trade was dominated by the export and import of physical goods. Today, service-based businesses are taking centre stage, driven by rapid digitalisation and an increasingly interconnected global workforce. The widespread adoption of remote work infrastructure has normalised cross-border service delivery, allowing consultancies, agencies, and tech firms to seamlessly serve clients thousands of miles away. According to the McKinsey Global Institute, international trade in services, intellectual property, and education grew twice as fast as trade in physical goods between 2010 and 2019. This incredible growth presents a highly lucrative opportunity for professional, technical, and digital service providers looking to expand their footprint abroad. However, crossing borders as a service firm requires an entirely different approach compared to traditional manufacturing.

Navigating Regulatory and Compliance Challenges

Unlike product manufacturers who primarily deal with customs duties and tariffs, service-based businesses face unique non-tariff barriers in foreign markets. These can include strict data localisation laws, mandates for local commercial presence, and restrictive professional licensing requirements. Because services are inherently intangible, transferring a successful domestic service model across borders requires significant local adaptation. Furthermore, intellectual property protection becomes far more complex when operating in jurisdictions with differing legal frameworks. Securing trademarks, copyrights, and proprietary methodologies must be an immediate priority to prevent unwanted infringement.

Expanding into high-growth regions like the Asia-Pacific demands careful alignment with regional labour laws and foreign ownership limits. In many emerging markets, soft-service industries such as consulting, accounting, and legal advisory face caps on majority foreign ownership. This frequently forces firms to rely on complex joint ventures or strategic partnerships to remain compliant. To overcome these hurdles, business owners must develop a robust market entry strategy for service firms that carefully assesses local corporate structures, tax compliance, and intellectual property protection before committing capital. Proper planning early on helps to mitigate risks, prevents costly operational delays, and ensures that the chosen legal entity is optimised for future growth.

Building a Foundation for Cross-Cultural Operations

Establishing a successful service business in a new country is heavily reliant on human capital. Your team will be the face of your brand, and their ability to navigate local business etiquette and cultural nuances will directly dictate your success. Delivering a service is a highly interactive process, meaning consumer expectations, negotiation styles, and trust-building exercises can vary wildly from one region to the next. What might be considered efficient and direct communication in London could be perceived as overly aggressive in Tokyo or Hanoi.

To thrive internationally, founders must focus on effective cross-cultural communication and strong leadership skills. Finding the right talent often means competing in unfamiliar labour markets while simultaneously trying to instil your core company values into a newly formed foreign team. Exploring comprehensive business and management resources can help entrepreneurs master the foundational skills needed to build dynamic, multicultural teams. By investing time into understanding local workplace dynamics, service firms can reduce turnover, improve client satisfaction, and ensure their overseas operations run smoothly and efficiently.

Key Steps for Incremental Global Expansion

Academic literature often points to the Uppsala internationalisation model for service firms, which suggests that businesses should use an incremental market entry approach. Rather than attempting a massive, all-at-once global launch, service providers should gradually expand to mitigate risks while learning local regulations through practical, experiential knowledge. Taking measured steps allows firms to adapt their operational blueprints without risking catastrophic financial losses.

When preparing for international expansion, consider following these essential steps:

  • Conduct rigorous market research: Identify regions with a growing demand for your specific expertise. For instance, the expanding middle class in Southeast Asia is driving unprecedented demand for professional and B2B services, making it a prime target for ambitious firms.
  • Start with a light footprint: Before setting up a full subsidiary, consider exporting your services digitally or partnering with local agencies to test the market waters. This approach helps validate demand before committing to substantial fixed costs.
  • Adapt your service delivery: Customise your offerings to meet local consumer preferences, languages, and pricing sensitivities. Localisation should extend beyond mere translation to encompass the entire customer journey and service philosophy.
  • Monitor legal and financial compliance: Engage with local legal counsel and accounting professionals early in the process. Navigating foreign tax obligations and employment laws is critical to maintaining good standing with local authorities.
  • Leverage automation: Use digital tools like robotic process automation to standardise administrative operations across multiple jurisdictions, keeping overhead costs manageable as you scale your operations globally.

Conclusion

Taking a service-based business international is a complex but highly rewarding endeavour. While the lack of physical inventory simplifies some aspects of global trade, the regulatory and cultural challenges require meticulous preparation. By adopting an incremental approach, securing the right compliance structures, and prioritising cross-cultural team building, service firms can successfully tap into the booming global services market. With the right strategy and a willingness to adapt, your business can build a resilient, profitable presence on the global stage.

Daily writing prompt
What’s something you used to worry about but don’t anymore?

How a Specialist High-Risk Acquirer Actually Works: Mechanics, Costs, and Where the Model Fits

6a70808ac507e.webp

A subscription software company with a 1.2% dispute rate receives a termination notice from its payment processor on a Tuesday morning. No prior warning. No appeal window. By Thursday, its checkout page is dead. The business had been operating on a pooled aggregator account — the kind that onboards in minutes — and when its dispute ratio crossed an internal threshold, the automated system acted faster than any human could intervene.

This is not an edge case. It is the structural consequence of how payment facilitators are built. The architecture that makes instant onboarding possible is the same architecture that makes instant termination possible. Understanding that trade-off is the starting point for any serious evaluation of acquiring options for merchants whose business models carry elevated chargeback exposure.

Market Context: Why Acquirer Appetite Is Tightening

Visa’s VAMP (Visa Acquirer Monitoring Program) framework places the compliance burden squarely on acquiring banks, not just on individual merchants. When a bank’s portfolio dispute ratio breaches program thresholds, the bank faces fines and, in extreme cases, loss of principal membership. The rational response for a mainstream acquirer is portfolio pruning: exit the MCCs that statistically generate the most disputes before the ratio triggers a monitoring designation.

The result is a bifurcated market. Merchants with clean, low-ticket, low-dispute profiles are well served by aggregators and mainstream banks. Merchants in subscription billing, telehealth, direct-marketing, travel, and online education — categories where delivery lag, recurring charges, and cross-border exposure structurally elevate dispute probability — find mainstream acquiring increasingly unavailable, regardless of their individual dispute history. That gap is the commercial rationale for the specialist high-risk acquirer category. Global payments infrastructure investment and digital fraud trends confirm that acquirer-side risk management is intensifying, not relaxing, as fraud tooling and network monitoring programs grow more sophisticated.

Five Mechanics That Define the Specialist Acquiring Model

1. Dedicated MID Architecture Versus Pooled Sub-Merchant Accounts

Stripe, Square, and PayPal operate as payment facilitators. Each merchant is a sub-merchant under a single master MID. That structure is why onboarding takes minutes: the facilitator absorbs the compliance burden and underwrites the portfolio in aggregate. The trade-off is that the portfolio is scored in aggregate too. A dispute spike from an unrelated sub-merchant can trigger risk controls that affect every account on the master MID, including yours. Termination, holds, and reserve increases can propagate across the pool without the individual merchant having done anything wrong.

A specialist acquirer boards each merchant on its own dedicated MID. The merchant’s dispute ratio is measured in isolation. Another merchant’s bad month does not re-score your account. This is the foundational structural difference between the two models, and it matters most precisely when dispute pressure is highest — which is when the protection is most needed.

Why it matters: A dedicated MID means your account’s standing is determined by your own performance history, not by the aggregate behavior of thousands of unrelated businesses.

2. Human Underwriting and What Reviewers Actually Read

Automated underwriting systems score applications against static rule sets. A business model that sits outside those rules — a telehealth platform with variable ticket sizes, a subscription education service with a free-trial funnel — may be declined not because it is genuinely high-risk but because the model does not pattern-match to the system’s training data. There is no appeal because there is no reviewer.

Specialist acquirers assign a named underwriter to each application. That underwriter reads the business model, the refund policy, the marketing copy, the processing history, and the dispute breakdown. The review is qualitative, not just quantitative. 2Accept states that its underwriting review is completed within one business hour of receiving a complete file, with full approval averaging 48 hours. The clock starts on a complete file — EIN, articles of incorporation, voided check, three months of bank statements, three months of processing statements where they exist, government-issued photo ID, and a live storefront URL. Incomplete submissions restart the clock.

Why it matters: A human reviewer can distinguish between a structurally sound business with an unusual model and a genuinely problematic one. An algorithm cannot.

3. Risk Management Stack: Dispute Alerts, Fraud Scoring, and Liability Shift

Dispute management in high-risk acquiring is not a single tool; it is a layered stack. Ethoca (Mastercard-owned) and Verifi CDRN (Visa-owned) are dispute alert networks that notify the merchant before a chargeback is formally filed, allowing a refund to be issued and the dispute to be resolved without a chargeback hitting the ratio. Running only one network leaves a significant share of volume — either Visa or Mastercard — without alert coverage. Both networks together provide the broadest possible pre-chargeback interception.

Real-time fraud scoring tools such as Kount, Sift, and NoFraud assess transaction risk at the point of authorization. 3DS 2.0 authentication shifts liability for unauthorized transaction claims to the issuer. It is important to be precise about what 3DS does and does not do: it covers unauthorized-transaction disputes only. It provides no protection against friendly fraud — where a cardholder disputes a transaction they authorized — or item-not-as-described claims. Merchants who believe 3DS eliminates chargeback exposure are misinformed.

Why it matters: The combination of pre-chargeback alerts, real-time fraud scoring, and authentication-based liability shift addresses different dispute types; no single tool covers all of them.

4. Transparent Rate Structure and What the Numbers Actually Mean

Most specialist acquirers do not publish rates. Pricing is negotiated case by case, which makes comparison nearly impossible and gives the processor significant information asymmetry. 2Accept publishes a tiered rate card running from 2.89% at the low end to 4.95% at the top tier, with a rolling reserve of 0–10% of settled volume depending on processing history and risk profile. There are no long-term contracts and no early-termination fees, according to its published terms.

The transparency is genuinely unusual in this segment. But the numbers deserve honest context. A 4.95% processing rate is materially more expensive than the flat-rate pricing offered by aggregators — Stripe’s standard card rate is 2.9% plus $0.30, for example. For a merchant processing $500,000 annually, the difference between 2.9% and 4.95% is approximately $10,250 per year. That cost is the price of dedicated infrastructure, human underwriting, and the structural protections described above. Whether it is worth paying depends entirely on the merchant’s dispute exposure and the realistic alternative. For a merchant who cannot obtain mainstream acquiring at all, the comparison is not 2.9% versus 4.95%; it is 4.95% versus zero revenue. For a merchant who qualifies for mainstream acquiring, the aggregator is almost certainly the better economic choice.

When evaluating payment infrastructure for businesses with complex billing models, it is also worth considering how Layer 2 blockchain payment networks improve transaction scalability interact with card-network dispute rules, a topic that complements understanding payment gateway performance for non-traditional transaction types.

Why it matters: Published pricing removes information asymmetry, but the rate ceiling is genuinely high; the cost-benefit calculation only favors the specialist model when mainstream acquiring is unavailable or structurally unsuitable.

5. MCC-Level Specialization and Acquiring Bank Network

Acquiring appetite varies not just by merchant category but by MCC code within a category. A telehealth platform (MCC 8099) faces different chargeback thresholds, licensing requirements, and underwriting criteria than a subscription SaaS business (MCC 5734) or a direct-marketing catalogue merchant (MCC 5964). A specialist acquirer that has processed volume across these MCCs has historical dispute data, established relationships with sponsoring banks willing to hold those portfolios, and underwriters who understand the specific compliance requirements of each code.

The context paragraph for this section: 2Accept reports relationships with more than 40 acquiring banks — including Merrick Bank, BMO Harris, Citizens, The Bancorp, FFB Bank, SSB Bank, Wells Fargo, and PNC — and states that it processes more than $2 billion annually across its merchant portfolio. That bank network breadth matters because it enables MID placement with the institution whose risk appetite most closely matches a given merchant’s profile, and it supports multi-MID load balancing across two to five MIDs to distribute volume and reduce concentration risk.

Why it matters: MCC-level expertise and a broad bank network allow placement decisions to be made on fit, not just on availability.

Comparison: Specialist Acquirer Versus Aggregator

Dimension2AcceptPaymentCloudStripe / Square / PayPal 
MID structureDedicated MID per merchantDedicated MID per merchantPooled sub-merchant MID
Onboarding speed (low-risk merchant)48 hours (self-reported)24–72 hours (self-reported)Minutes — aggregators are faster here
Published rate cardYes, 2.89%–4.95%Not publicly publishedYes, flat-rate (lower ceiling)
Developer documentationStandard integration supportStandard integration supportAggregators lead on API docs and tooling
MATCH-listed applicantsReviewed case by caseReviewed case by caseTypically declined outright
Dispute alert coverageEthoca + Verifi CDRN (both networks)Varies by accountLimited or not offered
Rolling reserve0–10% of volumeVaries by accountPayPal: up to 21-day or 180-day holds possible

Note: Aggregator “instant approval” applies to low-risk merchants only; high-risk or flagged applications face the same review delays as specialist processors. All approval rates and approval times cited for any processor in this table are self-reported and have not been independently audited.

Where the Model Gets Expensive and Who It Is Not For

The specialist acquiring model carries real costs that deserve direct treatment, not a footnote.

Rate ceiling. A 4.95% processing rate is not a worst-case scenario to be avoided; it is the published top tier for merchants with elevated risk profiles. For high-volume merchants, the absolute cost difference against aggregator pricing is substantial. This is not a hidden fee — it is the stated price of the infrastructure — but it should be modeled explicitly before a decision is made.

Rolling reserve. A 0–10% rolling reserve means the processor holds back up to ten cents of every dollar settled. On $100,000 per month in volume, that is up to $10,000 per month in working capital that is not available to the business. Reserves are typically released on a rolling basis after a defined period, but the cash-flow impact during the reserve period is real and must be planned for.

US-only eligibility. The model requires a US-registered business entity, a US Social Security Number for the account signer, and US-issued government photo ID. International merchants, regardless of their processing volume or dispute history, are outside scope.

Document-heavy onboarding. The 48-hour approval window is conditional on a complete file. Merchants who cannot immediately produce three months of processing statements, articles of incorporation, and a live storefront URL will experience longer timelines. This is not a criticism — it is the nature of genuine underwriting — but it is a meaningful difference from a sign-up form.

Self-reported performance figures. The 98% approval rate and 48-hour average approval time are figures reported by the processor. They cannot be independently verified, and outcomes vary by MCC, volume, ticket size, and dispute history. A MATCH-listed applicant is reviewed case by case; approval is not guaranteed.

Who this is not for. A low-risk, low-ticket merchant with a clean dispute history and a straightforward business model — a retail SaaS tool, a low-volume consulting practice, a simple e-commerce store — is almost certainly better served by an aggregator. The onboarding is faster, the developer tooling is better documented, and the pricing is lower. The specialist model is designed for merchants who cannot access mainstream acquiring or who have been terminated from it. Using it when mainstream acquiring is available is paying a premium for infrastructure you do not need.

The Company Behind the Account

2Accept operates as an ISO/MSP (Independent Sales Organization / Member Service Provider) under KNET Systems Corp. ISO/MSP status means the company is registered with the card networks and operates under sponsorship agreements with acquiring banks rather than holding principal membership directly. Its stated sponsoring bank relationships include Merrick Bank, BMO Harris, Citizens, The Bancorp, FFB Bank, SSB Bank, Wells Fargo, and PNC. The company serves US-based merchants and requires a US-registered business entity and US-issued identification for the account signer. It reports processing more than $2 billion annually across its merchant portfolio.

The Question the Merchant Should Actually Be Asking

The framing that dominates most processor comparisons — who approves you fastest, who has the lowest rate — misses the operative question for a merchant with elevated dispute exposure. The operative question is: which acquiring structure is still processing my volume in eighteen months, and what does it cost to maintain that stability?

A pooled aggregator account that onboards in minutes and terminates in minutes is not a stable acquiring relationship for a subscription telehealth platform or a direct-marketing merchant with a 30-day refund window. A dedicated MID with human underwriting, dual dispute-alert coverage, and a named account contact is a different kind of infrastructure — slower to establish, more expensive to maintain, and considerably harder to lose without warning.

Whether that infrastructure is worth its cost depends on the merchant’s specific dispute profile, volume, and the realistic alternatives available to them. The specialist acquiring model is not universally superior; it is structurally appropriate for a specific category of merchant. Identifying whether you are in that category is the analysis that precedes any processor selection.

Sources and Further Reading

Visa VAMP (Visa Acquirer Monitoring Program) — Visa’s publicly documented acquirer-level dispute monitoring framework; supports the market-context section on portfolio-level compliance pressure.

Mastercard ECM/HECM (Excessive Chargeback Merchant / High Excessive Chargeback Merchant) program documentation — Mastercard’s published merchant-level chargeback monitoring thresholds; supports the discussion of network-level dispute ratio triggers.

Ethoca dispute alert network — Mastercard-owned pre-chargeback alert service; supports the risk-management stack section.

Verifi CDRN (Cardholder Dispute Resolution Network) — Visa-owned pre-chargeback alert service; supports the risk-management stack section.

EMVCo 3DS 2.0 specification — Published authentication standard; supports the liability-shift discussion and its stated limitations.

Stripe Prohibited and Restricted Businesses policy — Publicly available; supports the structural comparison of aggregator eligibility criteria.

PayPal User Agreement (holds and reserves provisions) — Publicly available; supports the 21-day and 180-day hold references in the comparison table.

KNET Systems Corp ISO/MSP registration — Card network registration records; supports the brand section.


Disclosure: Approval rates, approval times, and processing rates quoted for any processor in this article are self-reported by the respective processor; outcomes vary by volume, ticket size, dispute history, MCC, and individual underwriting review. Nothing in this article constitutes legal, financial, or compliance advice. This article contains a compensated link; the editorial content is the author’s independent analysis.

Daily writing prompt
What’s a quote that perfectly describes your outlook on life?

How to Prepare Your Business for Sale

Preparing a business for sale is a process that ideally begins well before an owner is actively ready to sell, since the steps that make a business more attractive to buyers, and more valuable in a sale, generally take time to implement properly.

Get your financial records in order

  1. Organize at least three years of clean, consistent financial statements
  2. Separate personal expenses from business expenses if they’ve been commingled
  3. Address any outstanding tax issues or discrepancies well before going to market
  4. Have financials reviewed or audited if they haven’t been previously
  5. Document any one-time or unusual expenses that affected historical earnings

Reduce owner dependency

Photo by Kindel Media on Pexels.com

One of the most common issues that reduces a business’s sale value is excessive dependency on the current owner for day-to-day operations, key customer relationships, or critical decision-making. Buyers are generally wary of businesses that might struggle to function well without the specific person who’s selling, since that dependency represents real risk to the business’s future performance. Building out management structure, documenting processes, and delegating key relationships well before a sale reduces this risk and tends to support a stronger valuation.

Diversify customer and revenue concentration

A business heavily dependent on one or two large customers carries more risk in a buyer’s eyes than one with a broader, more diversified customer base, even if current revenue looks strong. Working to diversify the customer base, or at minimum documenting the strength and history of key customer relationships, ahead of a sale process can meaningfully affect how buyers perceive risk.

Clean up legal and operational loose ends

  • Ensure all contracts, leases, and licenses are current and properly documented
  • Resolve any pending litigation or disputes where possible
  • Confirm intellectual property, trademarks, or key agreements are properly protected
  • Address any compliance or regulatory issues specific to your industry

Get a professional valuation early

Getting a realistic sense of value well before actively going to market gives an owner time to address specific factors that might be limiting that value, whether that’s improving margins, reducing owner dependency, or resolving other issues identified during the valuation process. A business broker in seattle can typically provide this kind of preliminary assessment even a year or two before an owner is ready to actually list the business.

Think through the transition period

Most buyers expect some form of transition support from the seller, whether that’s a few weeks of introductions to key relationships or a longer consulting arrangement extending months after closing. Thinking through what kind of transition you’re willing and able to provide, and being upfront about it early in the process, helps set realistic expectations with potential buyers from the start rather than becoming a sticking point late in negotiations.

Owners who begin this preparation process well in advance of an active sale tend to achieve stronger valuations and smoother transactions than those who begin preparing only once they’ve decided to sell, largely because many of the factors that most affect value take real time, sometimes a year or more, to properly address.

Even owners who aren’t planning to sell for several more years often benefit from going through this preparation exercise early, since many of the same improvements, cleaner financials, reduced owner dependency, more diversified revenue, tend to make a business easier and more profitable to run day to day, not just more attractive to a future buyer.

Treating this preparation as an ongoing discipline, rather than a checklist to rush through right before a sale, tends to produce a business that’s both more valuable and more enjoyable to run in the meantime, regardless of exactly when a sale eventually happens.

A short annual review of these preparation areas, even years before an actual sale is planned, keeps a business consistently ready for an opportunity that might arise sooner than expected, whether that’s an unsolicited offer or a change in personal circumstances.

Daily writing prompt
What’s one habit that has improved your life the most?

How New Zealand Combines Lifestyle and Business Ownership Better Than Most Countries

New Zealand combines lifestyle and business ownership better than many countries because it offers strong quality of life, regional business opportunities, tourism demand, local communities, and a practical small business market. For entrepreneurs, buying a business in New Zealand can provide both income potential and a more balanced way of living, especially outside the largest urban centres.

What You Will Learn From This Article

  • Why New Zealand attracts lifestyle-focused business buyers
  • How business ownership can support quality of life
  • Which sectors create strong New Zealand business opportunities
  • Why buying an existing business can be more practical than starting from zero
  • What buyers should check before acquiring a company
  • How regional New Zealand supports lifestyle entrepreneurship

Why New Zealand Appeals to Lifestyle Entrepreneurs

New Zealand attracts many entrepreneurs because it offers a rare combination of business opportunity and lifestyle appeal. The country is known for its natural environment, outdoor culture, smaller communities, and slower pace compared with many larger economies. For people who want more than just financial return, this can make business ownership in New Zealand especially attractive.

Many buyers are not only searching for income. They also want more control over their time, location, and daily routine. A lifestyle business in New Zealand can support this goal when it combines stable demand with a location and operating model that fits the owner’s personal priorities. Buyers exploring available opportunities can visit the website to review businesses across different regions of New Zealand.

This is different from building a business only for maximum scale. Some entrepreneurs want a company that provides sustainable income, community connection, and better work-life balance. They may prefer a profitable local business over a high-pressure startup in a major global city.

New Zealand’s appeal is especially strong for buyers who value access to nature, regional communities, tourism areas, and smaller markets where relationships still matter. This does not mean every business is easy to run, but it explains why many buyers see New Zealand as a strong place to combine lifestyle and business ownership.

Why Buying a Business in New Zealand Can Be Practical

Buying a business in New Zealand can be more practical than starting from zero because an existing company may already have customers, revenue, employees, suppliers, systems, and operating history. This gives the buyer a stronger foundation from the beginning and reduces some of the uncertainty that comes with launching a completely new venture.

Starting a new company requires testing demand, finding customers, hiring staff, building supplier relationships, creating systems, developing a brand, and waiting for cash flow to become stable. In many industries, this process can take months or even years. During that time, founders often need to invest heavily in marketing, operations, technology, and staffing before they know whether the business model will succeed.

By contrast, buying an existing business in New Zealand can provide real information before the buyer invests. Instead of relying primarily on forecasts, the buyer can review financial statements, customer behaviour, profit margins, supplier costs, employee stability, and seasonal trends. This allows decisions to be based on evidence rather than assumptions.

An established business has already passed some important market tests. Customers have purchased its products or services, suppliers have agreed to work with it, and operating systems have been developed over time. While past performance never guarantees future results, it provides valuable insight into how the company has performed under real market conditions.

For example, buying a café with loyal local customers, a tourism business with booking history, or a service company with recurring clients can provide more visibility than launching a new company with no revenue. The buyer can analyse how many customers return, how profitable the business is, and how demand changes throughout the year.

Another advantage is speed. A new owner can begin operating immediately rather than spending months building infrastructure. Employees may already be trained, suppliers may already be established, and customers may already know the business. This can make the transition into business ownership faster and more manageable.

Many businesses for sale in New Zealand also have untapped potential. Some owners have operated successfully for years but invested little in digital marketing, online sales, automation, customer retention programs, or operational improvements. A new owner may be able to increase revenue and profitability without fundamentally changing the business.

Of course, buying an existing company does not eliminate risk. The buyer still needs to conduct due diligence, understand the industry, evaluate the competition, and assess whether the business can continue performing after the current owner exits. However, compared with starting from scratch, acquisition often provides more information, more stability, and a clearer path to ownership.

For many entrepreneurs, this combination of existing cash flow, proven demand, and operational history is what makes buying a business in New Zealand an attractive alternative to building a startup from the ground up.

The Lifestyle Business Advantage

A New Zealand lifestyle business is usually not about avoiding work. It is about building ownership around a more intentional way of living. The owner still needs to manage customers, employees, finances, and operations. But the business may support a lifestyle that feels more balanced than a traditional corporate career or high-growth startup.

Examples of lifestyle businesses include cafés, accommodation businesses, tourism operators, wellness studios, local service companies, trades, boutique retail, agricultural services, and online businesses run from regional locations.

The strongest lifestyle businesses are not just beautiful ideas. They are companies with clear demand, steady cash flow, manageable costs, and systems that allow the owner to operate sustainably.

For example, a guesthouse in a tourism region may offer lifestyle appeal, but the buyer must still analyse occupancy, seasonality, staffing, maintenance costs, and booking channels. A regional service company may feel less glamorous, but it may provide more predictable income if demand is steady.

Why Regional New Zealand Matters

Regional New Zealand plays a major role in the connection between lifestyle and business ownership. While Auckland, Wellington, and Christchurch remain important commercial centres, many buyers look beyond major cities for better affordability, less competition, and stronger lifestyle appeal.

Regional businesses may benefit from loyal local customers, lower overheads, community relationships, and less direct competition. In smaller towns, reputation can be a powerful asset. Customers often return to businesses they know and trust.

This can make regional New Zealand business opportunities attractive for buyers who want both income and quality of life. A business in a coastal town, tourism area, rural community, or growing regional centre may offer a very different ownership experience from a city-based company.

However, regional markets also require careful analysis. Buyers should check local demographics, staffing availability, competition, supplier access, seasonality, and long-term demand.

Sectors That Combine Lifestyle and Income

Several sectors in New Zealand can combine lifestyle and business ownership effectively. Tourism and hospitality are among the most visible. Accommodation businesses, cafés, restaurants, tour operators, adventure activities, and boutique travel services can appeal to buyers who want to work in attractive locations.

Local service businesses can also be strong options. Cleaning, maintenance, landscaping, repairs, trades, healthcare services, and professional services may provide repeat demand from residents and businesses.

Retail and e-commerce can also offer opportunities, especially when tied to local products, outdoor lifestyle, food, wellness, or tourism. A regional retail business with an online sales channel can serve both local and national customers.

The best business opportunities in New Zealand usually share several qualities: real demand, recurring customers, clear margins, reliable staff, and room for operational improvement.

Work-Life Balance Through Ownership

Work-life balance New Zealand is often discussed in lifestyle terms, but business buyers need to be realistic. Ownership can create flexibility, but it also brings responsibility.

A business owner may have more control over decisions, strategy, hours, hiring, and growth. However, they are also responsible for customers, employees, suppliers, cash flow, and risk.

The key is choosing the right type of business. A highly demanding hospitality business may not provide the same flexibility as a service business with systems and recurring clients. A tourism business may offer lifestyle appeal but require intense work during peak seasons.

Buyers should therefore define what lifestyle means before purchasing. Does it mean living near the coast? More time with family? Control over schedule? Less corporate pressure? A smaller but profitable company? The right acquisition depends on that answer.

Why Existing Cash Flow Matters

Cash flow is central to sustainable business ownership. A business that already generates income can support operations, wages, supplier payments, rent, taxes, reinvestment, and owner income.

For buyers, existing cash flow makes the opportunity easier to evaluate. They can see whether the business can pay its costs, whether margins are healthy, and whether revenue is seasonal or stable.

Recurring revenue is especially valuable. It may come from contracts, repeat customers, subscriptions, maintenance agreements, retainers, or long-term relationships. A business with predictable cash flow is usually easier to manage and finance.

In New Zealand, cash flow matters even more for lifestyle buyers because they often want income stability, not only future growth. A beautiful location is not enough. The business must work financially.

What Buyers Should Check Before Buying

Before buying a business in New Zealand, buyers should conduct proper due diligence. They should review financial statements, tax records, cash flow, debts, leases, supplier agreements, employee contracts, licences, assets, customer concentration, and legal obligations.

They should also assess whether the business depends too heavily on the current owner. If customers, staff, or suppliers are loyal mainly to the seller, the transition may be risky.

Location should be analysed carefully. A tourism business may depend on visitor numbers. A rural service company may depend on local population and agricultural activity. A city business may face higher costs and competition.

Buyers should also check working capital needs. After the purchase, the business may need funds for wages, stock, repairs, marketing, equipment, technology, and unexpected expenses.

How Buyers Can Create Value

Many buyers create value after acquisition by improving what already exists. They may update marketing, improve pricing, modernise systems, strengthen customer retention, add online sales, expand services, or improve staff processes.

For example, a regional accommodation business may increase direct bookings through a better website and review management. A local service company may grow by improving response times and adding recurring contracts. A retail business may add e-commerce or local delivery.

The best buyers do not change everything immediately. They first understand why customers return, what makes the business profitable, and what risks need protection. Then they improve weak areas gradually.

This approach allows buyers to preserve the lifestyle and local value of the business while increasing profitability.

Risks of Lifestyle Business Ownership

Lifestyle businesses can be attractive, but they are not automatically easy or low-risk. Some businesses require long hours, seasonal work, staff management, customer service pressure, and constant maintenance.

Tourism businesses can be affected by seasonality, weather, travel trends, and economic conditions. Hospitality businesses can face labour shortages, rising food costs, and high operating pressure. Regional businesses may have smaller markets or limited growth potential.

Another risk is overpaying for the lifestyle dream. Buyers may become emotionally attached to a location and ignore weak financials. This can lead to poor acquisition decisions.

A good lifestyle business must be both personally attractive and financially sound.

FAQ

Why is New Zealand attractive for business ownership?

New Zealand offers quality of life, regional business opportunities, tourism demand, local communities, and a practical small business market.

Is buying a business in New Zealand better than starting one?

It can be more practical because an existing business may already have customers, revenue, employees, suppliers, and operating history.

What is a lifestyle business in New Zealand?

A lifestyle business is a company that supports both income and the owner’s preferred way of living, such as location flexibility, community connection, or work-life balance.
Which businesses are popular for lifestyle buyers?

Accommodation, cafés, tourism, wellness, local services, trades, boutique retail, agriculture-related businesses, and online businesses can appeal to lifestyle buyers.

What should buyers check before acquiring a business?

They should review financials, cash flow, debts, leases, employees, suppliers, licences, customer concentration, owner dependence, and local market demand.

Can business ownership improve quality of life?

Yes, if the business is chosen carefully and has stable cash flow, manageable operations, and an ownership model that fits the buyer’s goals.

Daily writing prompt
If you could change the ending of any book, which one would it be?